Macro at a Glance
Germany's Bundestag approved a significant budget overhaul on March 18, eliminating the nation's strict 0.35% GDP debt constraint. With parliamentary support exceeding two-thirds, "Europe's largest economy has decided to increase its budget by 1000 billion euros for national infrastructure," potentially revitalizing a nation experiencing two years of economic contraction. Defense spending also received relief from previous limitations.
This represents a fundamental shift in German fiscal philosophy, potentially advantaging Friedrich Merz's anticipated chancellorship. European defense manufacturers and German industrial sectors emerged as primary beneficiaries. However, neighboring nations face uncertain implications, as elevated Eurozone interest rates resulting from German debt issuance complicate financing for other countries.
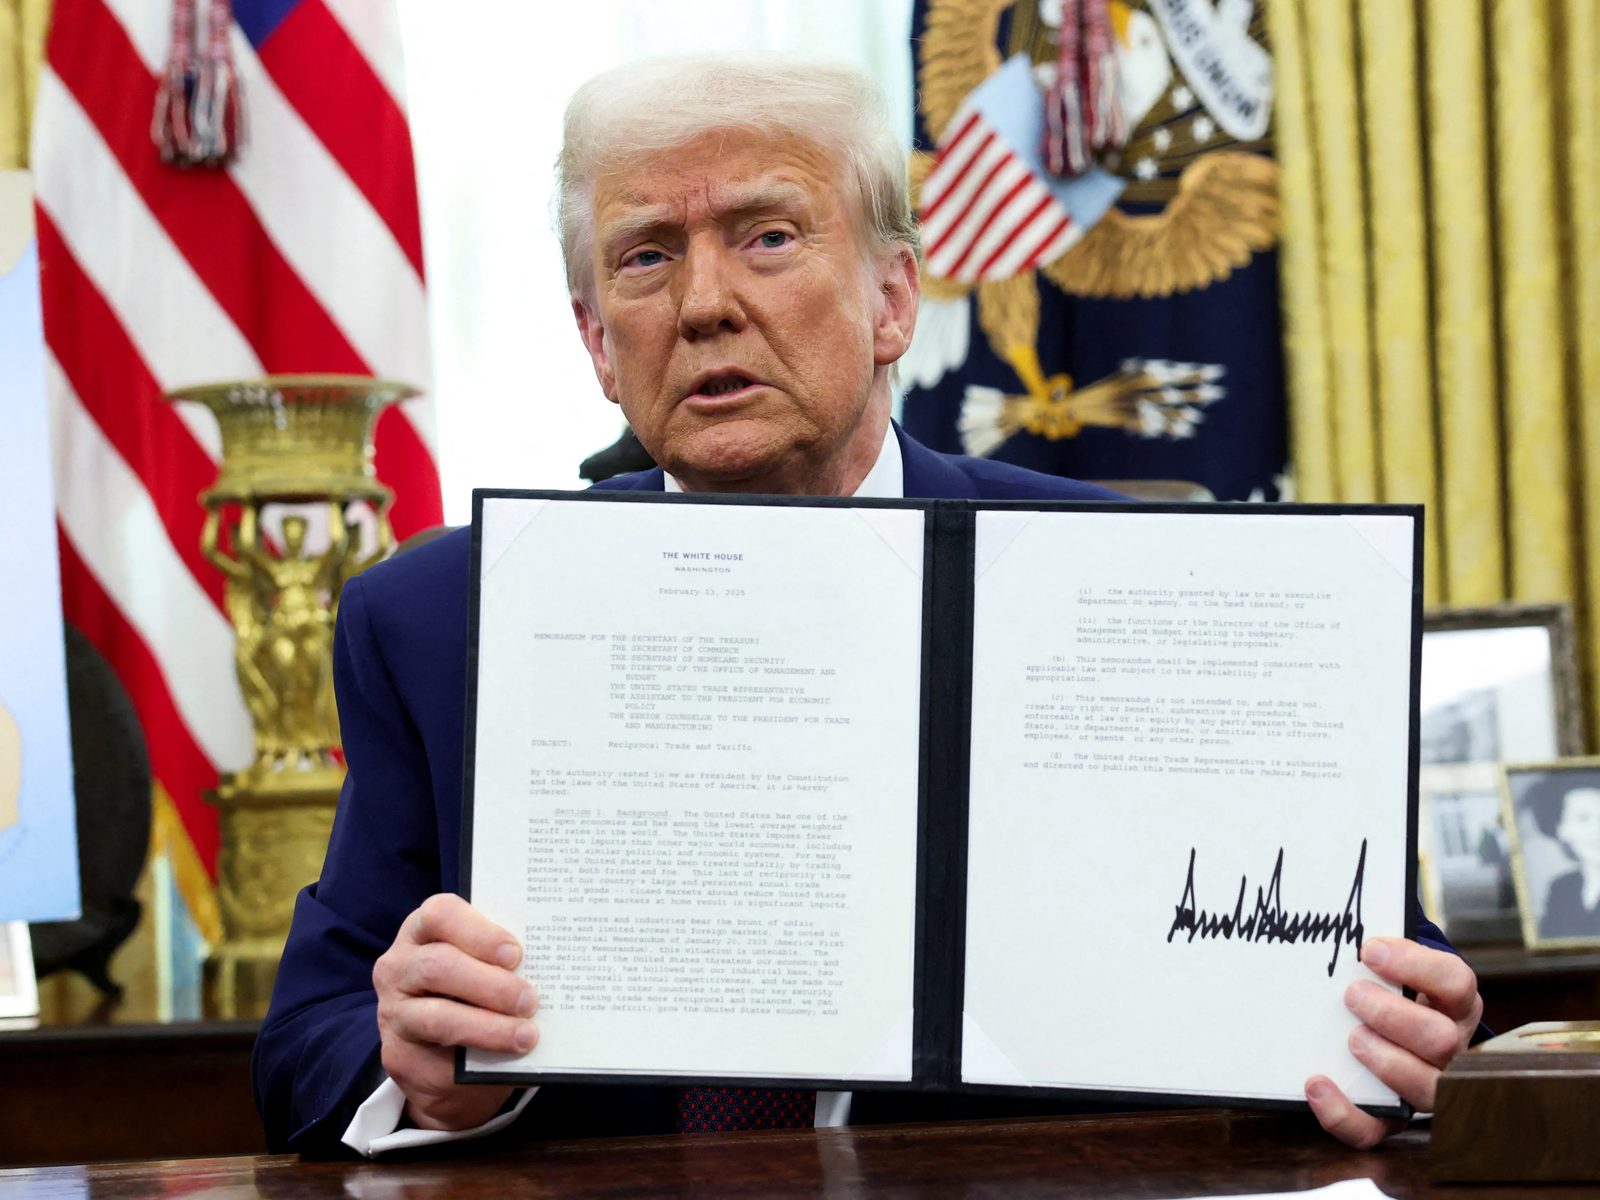
U.S. equities experienced significant volatility throughout March, with the S&P 500 declining by more than 5.75% amid resurgent stagflation apprehensions. President Trump's escalated trade tensions prompted corresponding retaliation from affected nations. Simultaneously, inflation exceeded expectations—"core PCE for February rose by 0.5%," raising concerns about price stability. With the Federal Reserve maintaining rates at 4.25-4.5% and signaling no imminent reductions, market anxiety intensified considerably.
On March 19, Japan's central bank preserved its policy rate unchanged, as anticipated, despite persistent inflationary headwinds. The decision reflected cautious positioning amid uncertainty surrounding U.S. tariff implications. Market observers anticipate rate increases in June or July, maintaining a measured tightening trajectory of approximately one adjustment per half-year until terminal rates are achieved.
One Sector, One Insight
Basic Materials and Energy
TotalEnergies officially resumed its $20 billion Mozambique liquefied natural gas initiative during March, representing a pivotal development for African energy infrastructure. Having paused operations since 2021 due to security constraints, renewed progress generated optimism. The announcement triggered a 3.2% appreciation in company shares. The venture commenced following the 2010 discovery of approximately 65 trillion cubic feet of recoverable natural gas reserves offshore. With TotalEnergies maintaining a 26.5% operating stake, the U.S. Export-Import Bank's re-approval of nearly $5 billion in financing proved instrumental in surmounting previous obstacles delaying this undertaking.
Consumption and General Public Services
Walgreens Boots Alliance capitulated to a $13 billion acquisition proposal from Sycamore Partners on March 6, terminating a prolonged struggle with diminishing revenues, compressed pharmacy profitability, and intensified e-commerce rivalry. The arrangement included a thirty-five-day assessment window permitting alternative bid consideration. Sycamore intends comprehensive restructuring centered on domestic market optimization, expense reduction, and potential Boots UK separation to restore viability.
Financial Services
Switzerland's Federal Council announced stricter capital mandates for systemically critical financial institutions on March 20, directly addressing UBS following its Credit Suisse acquisition. Proposed equity requirement enhancements aim to mitigate systemic exposure, though UBS contends such measures undermine competitive positioning globally. UBS leadership cautioned that heightened restrictions might necessitate operational relocation. Subsequently, the institution adopted reconciliatory language regarding potential investment banking contraction to circumvent amplified capital obligations.
Healthcare
Zealand Pharma established a collaborative arrangement with Roche on March 11 for co-developing Petrelintide, an advanced weight-loss therapeutic candidate. Valued at $5.3 billion, this partnership represented substantial progress for Zealand and demonstrated Roche's commitment to capturing market share in the rapidly expanding obesity treatment sector. Roche shares advanced 3.6%, while Zealand Pharma appreciated 38% following disclosure.
Industrials
Electric vehicle markets displayed considerable instability throughout March. Build Your Dreams (BYD) surpassed Tesla as the sector's dominant player, demonstrating "revenues soared 29% to $107 billion last year" versus Tesla's $98 billion. BYD's hybrid-inclusive approach contrasts with Tesla's pure-electric concentration. Since January's commencement, BYD appreciated 41% while Tesla declined 31%. The competitive dynamic has shifted substantially in favor of the Chinese manufacturer.
Technology and Network Equipment
Following prior regulatory-driven abandonment, Alphabet and Wiz negotiated a $32 billion acquisition agreement for the cloud-security enterprise. Wiz—operating from Israel and the United States—collaborates extensively with major providers including AWS and Microsoft Azure. Alphabet shares decreased nearly 3% post-announcement, representing continuation of broader year-to-date weakness.
Stock of the Month
Novo Nordisk experienced its most severe monthly performance since 2002, with valuations declining over 22%. Decelerated U.S. prescription volume for obesity medication Wegovy, heightened competitive threats, and regulatory pressure catalyzed dramatic reversal. The Danish manufacturer surrendered its standing as Europe's premier listed corporation to SAP.
Key Performances (As of March 31, 2025)
| Index/Asset | Value | Monthly Change | YTD Change |
|---|---|---|---|
| S&P 500 | 5611.85 | -5.75% | -4.59% |
| Dow Jones | 42001.76 | -4.20% | -1.28% |
| NASDAQ | 17299.29 | -8.29% | -10.49% |
| FTSE 100 | 8582.81 | -2.58% | 5.01% |
| CAC 40 | 7790.71 | -3.96% | 5.55% |
| DAX | 22163.49 | -1.72% | 11.32% |
| SMI 20 | 12598.12 | -3.12% | 8.38% |
| MSCI World | 3628.87 | -4.60% | -1.97% |
| VIX | 22.28 | 13.50% | 28.41% |
| CHF/USD | 1.1305 | 1.76% | 2.14% |
| CHF/EUR | 1.0449 | -2.23% | -1.77% |
| Brent ($/bbl) | 74.63 | 1.98% | -1.71% |
| Gold Spot ($/oz) | 3155.50 | 9.44% | 21.08% |
Upcoming Events
- April 10: US CPI
- April 17: BCE
- April 22: Tesla Q1 earnings